Australians paying by card are about to see one of the most visible changes to everyday checkout costs in years.
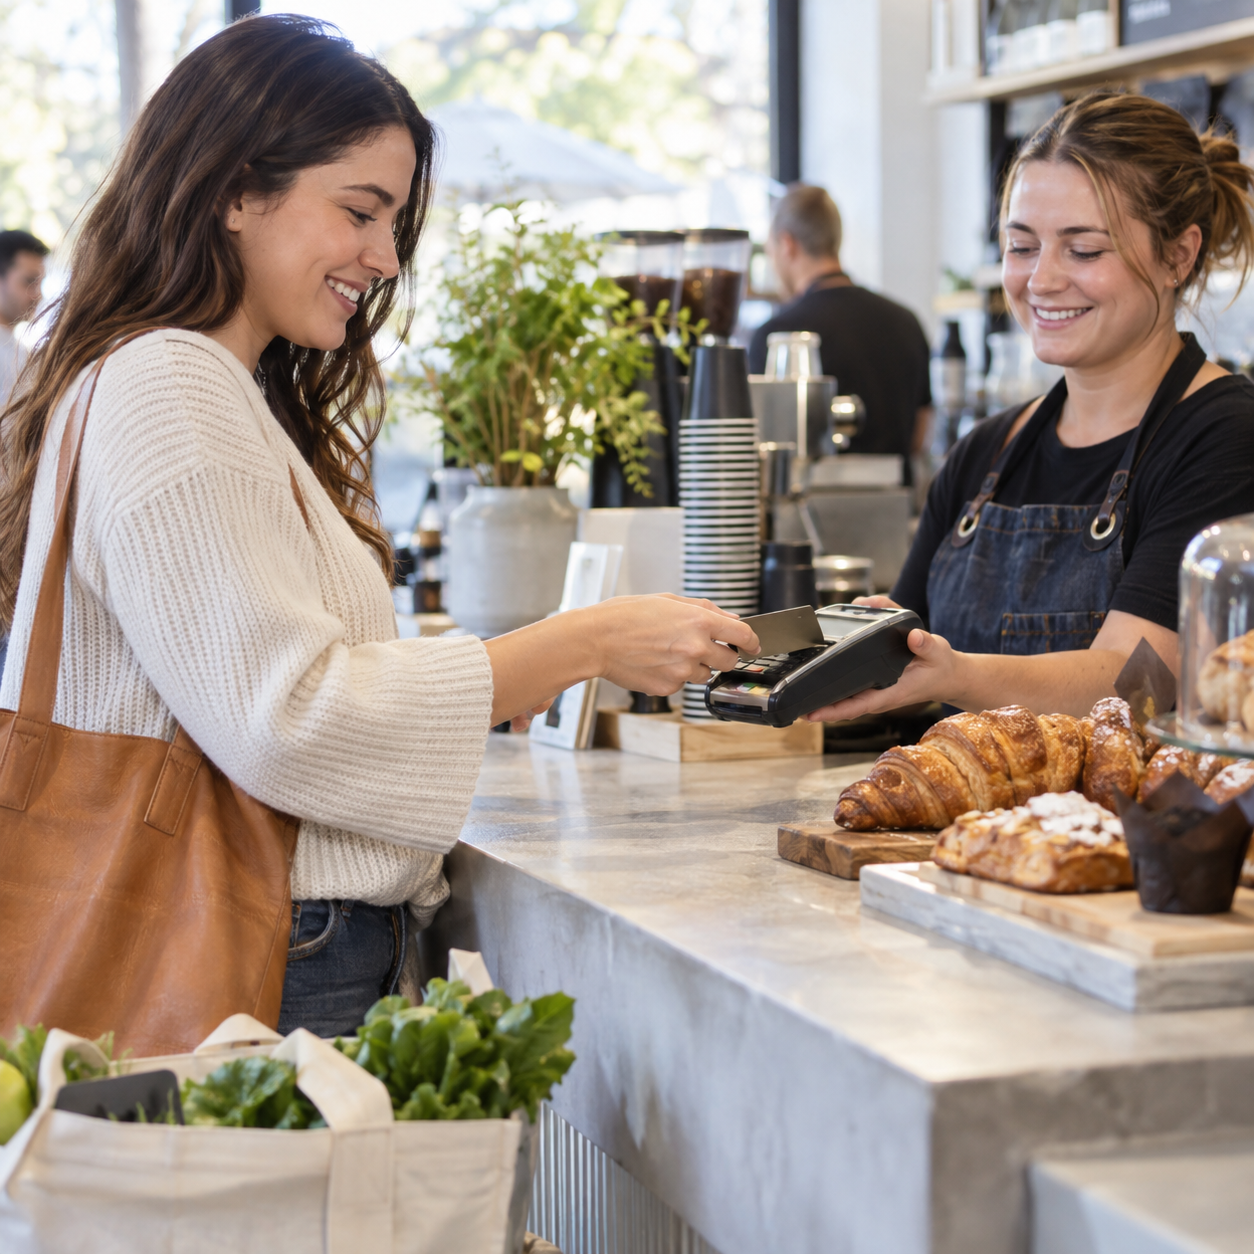
From 1 October 2026, eftpos, Mastercard and Visa will introduce no-surcharge rules after the Reserve Bank of Australia changed the regulatory framework that had previously prevented those card networks from banning merchant surcharges.
American Express and UnionPay have also said they will remove surcharging from 1 October, while PayPal’s change is due from 5 October.
For shoppers, the practical effect is simple in many common situations: the extra percentage or fixed card fee that appears at the terminal should disappear for the covered payment methods.
But the reform does not mean every extra fee in Australia disappears, and it does not mean card acceptance becomes free for businesses.
What exactly changes on 1 October?
The Reserve Bank says card surcharging on both debit and credit cards should end for the major designated networks from 1 October.
Rather than directly regulating every merchant, the RBA has removed its prohibition on “no-surcharge” rules. The card networks can then require businesses that accept their cards not to add a separate card-payment surcharge.
eftpos, Mastercard and Visa have each said they will introduce those rules from the start date.
For many businesses, payment service providers are expected to disable surcharge functionality on payment terminals around the same time.
That means a café that currently adds, for example, a separate percentage when a customer taps a Visa or Mastercard would generally need to stop imposing that card surcharge under the new network rules, subject to any specific exception that may apply.
What does not disappear?
This is where the reform can easily be misunderstood.
The RBA says the change applies to a surcharge added because the customer chooses to pay by card. It does not automatically remove weekend surcharges, public holiday surcharges, booking fees or service fees.
Those charges are different because they are not necessarily tied to the card network used for payment.
A restaurant can still have a clearly disclosed Sunday surcharge if consumer law allows it. A ticket seller can still charge a legitimate service or booking fee if the pricing is presented lawfully. A business’s payment provider can still charge the merchant for terminal rental or transaction processing.
The reform is therefore best understood as ending the separate card-payment surcharge for the networks covered by the new rules, not as a ban on all additional charges in the economy.
Businesses will still pay to accept cards
Card payments create costs for merchants. Businesses pay acquirers and payment service providers for processing, terminals and other services.
From October, businesses that currently pass those costs directly to card users through a surcharge will generally need to handle them in another way.
The RBA says businesses can reflect card acceptance costs in their overall prices, which is consistent with the idea that the advertised price should more closely match what most customers actually pay.
Some businesses may decide to absorb the cost. Others may increase base prices slightly. Some may shop around for a cheaper payment provider or change the payment methods they encourage customers to use.
Businesses can also offer discounts for particular payment methods rather than adding a surcharge to cards.
The RBA is cutting some underlying fees too
The surcharge change is only one part of a wider payments reform.
From 1 October, the RBA is also lowering interchange fee caps for domestic card transactions.
For consumer credit cards, the maximum interchange cap will be 0.30 per cent of transaction value. Commercial credit cards will have a maximum cap of 0.80 per cent.
For debit and prepaid cards, the cap will be 0.16 per cent of transaction value or 8 cents per transaction, with the existing weighted-average benchmark retained.
Interchange is only one component of the total fee a business may pay to accept a card, so a lower cap does not mean every merchant’s payment bill falls by the same amount.
The RBA’s stated aim is to put downward pressure on merchant costs, with smaller businesses expected to benefit because they have often paid fees closer to existing caps.
Will shoppers really save money?
Consumers who frequently pay card surcharges should see those separate fees vanish on covered transactions.
The RBA’s review estimated that Australians pay about $1.6 billion a year in card surcharges, a figure widely cited in current reporting about the change.
That does not mean households will keep the entire amount dollar-for-dollar.
If some businesses raise advertised prices to recover card-processing costs, part of the savings from removing visible surcharges could be offset through general pricing.
The RBA has acknowledged that businesses which currently surcharge may incorporate payment costs into their normal prices.
The policy argument is that this creates clearer pricing: customers see one price rather than discovering an unavoidable fee when they reach the terminal.
Whether an individual shopper is better off will depend on where they shop, how they pay and how businesses adjust their prices.
Why the RBA decided the old system was no longer working
Card surcharging was originally intended to create a price signal. If one payment method cost a merchant more, the customer using it could be charged more and might choose a cheaper alternative.
The Reserve Bank concluded that the system had become less effective as cash use declined and card payments became harder to avoid.
It also found that consumers and businesses considered the rules complex, surcharges were not always well disclosed, and some merchants charged the same surcharge across different card types even when their acceptance costs differed.
The RBA’s consumer research indicated strong support for ending surcharging and moving payment costs into transparent advertised prices.
What small businesses should do before October
The RBA says the first point of contact should be the business’s payment service provider.
Major providers have been contacting merchants about how terminals and payment settings will change.
Businesses that currently surcharge should understand whether the surcharge function will be disabled automatically, whether online checkout settings also need to change and what their new merchant fees will be.
They should also review pricing rather than simply assuming they must absorb all costs unchanged.
The Reserve Bank encourages merchants to compare payment providers and plans. Fewer than one in ten businesses switched provider in 2024–25, according to material considered in the review, suggesting some may be able to reduce costs by shopping around.
Businesses with regulated prices may face a different challenge if they cannot easily alter their prices. The RBA says governments and price regulators have been informed so the change can be considered in future pricing decisions.
Invoices and business-to-business payments are not automatically exempt
The start date is based on when a card payment is made, not simply when an invoice was issued.
The RBA says a card payment made on or after 1 October may no longer be surchargeable even if the invoice was sent before that date.
Businesses should check with their payment provider because terminal or online-payment functionality may change automatically.
Business-to-business card transactions are also not automatically excluded. An exemption would need to come from a card network’s rules or from law or regulation.
There are later stages in the reform
The payments overhaul continues beyond October.
By 30 October 2026, designated card networks and large acquirers are due to begin publishing specified information about card-payment fees.
By 30 January 2027, large acquirers are required to publish information about how interchange reductions have flowed through to merchant service fees.
From 1 April 2027, interchange caps will also apply to foreign-issued card transactions acquired in Australia, and merchants are due to receive more detailed statements about payment costs.
Those transparency measures are intended to make it easier for businesses to compare providers and negotiate better deals.
Credit-card rewards may change too
Some banks and card issuers have already announced changes to rewards, pricing or other benefits as the economics of card payments shift.
The RBA notes that issuers decide how to structure individual credit-card products. Lower interchange revenue can influence those commercial decisions, but there is no single mandatory change to rewards programs.
Consumers with rewards cards should therefore check updated product terms rather than assuming points, lounge access, insurance or annual fees will stay the same.
The simplest takeaway
From 1 October, the familiar card surcharge should largely disappear across eftpos, Mastercard, Visa, American Express and UnionPay transactions, with PayPal following from 5 October.
That does not eliminate every checkout fee, and businesses will still face payment-processing costs.
The larger reform is designed to shift those costs away from a separate last-minute card charge and toward clearer pricing and lower underlying payment fees.
For shoppers, the key is to look at the final advertised price. For small businesses, the key is to understand the new terminal rules, review provider fees and decide how payment costs fit into overall pricing before 1 October arrives.