Australia’s long-running argument over whether superannuation should help people buy a home has returned to federal politics, with Shadow Housing Minister Andrew Bragg floating several options and Treasurer Jim Chalmers warning against changes that could reduce retirement savings.
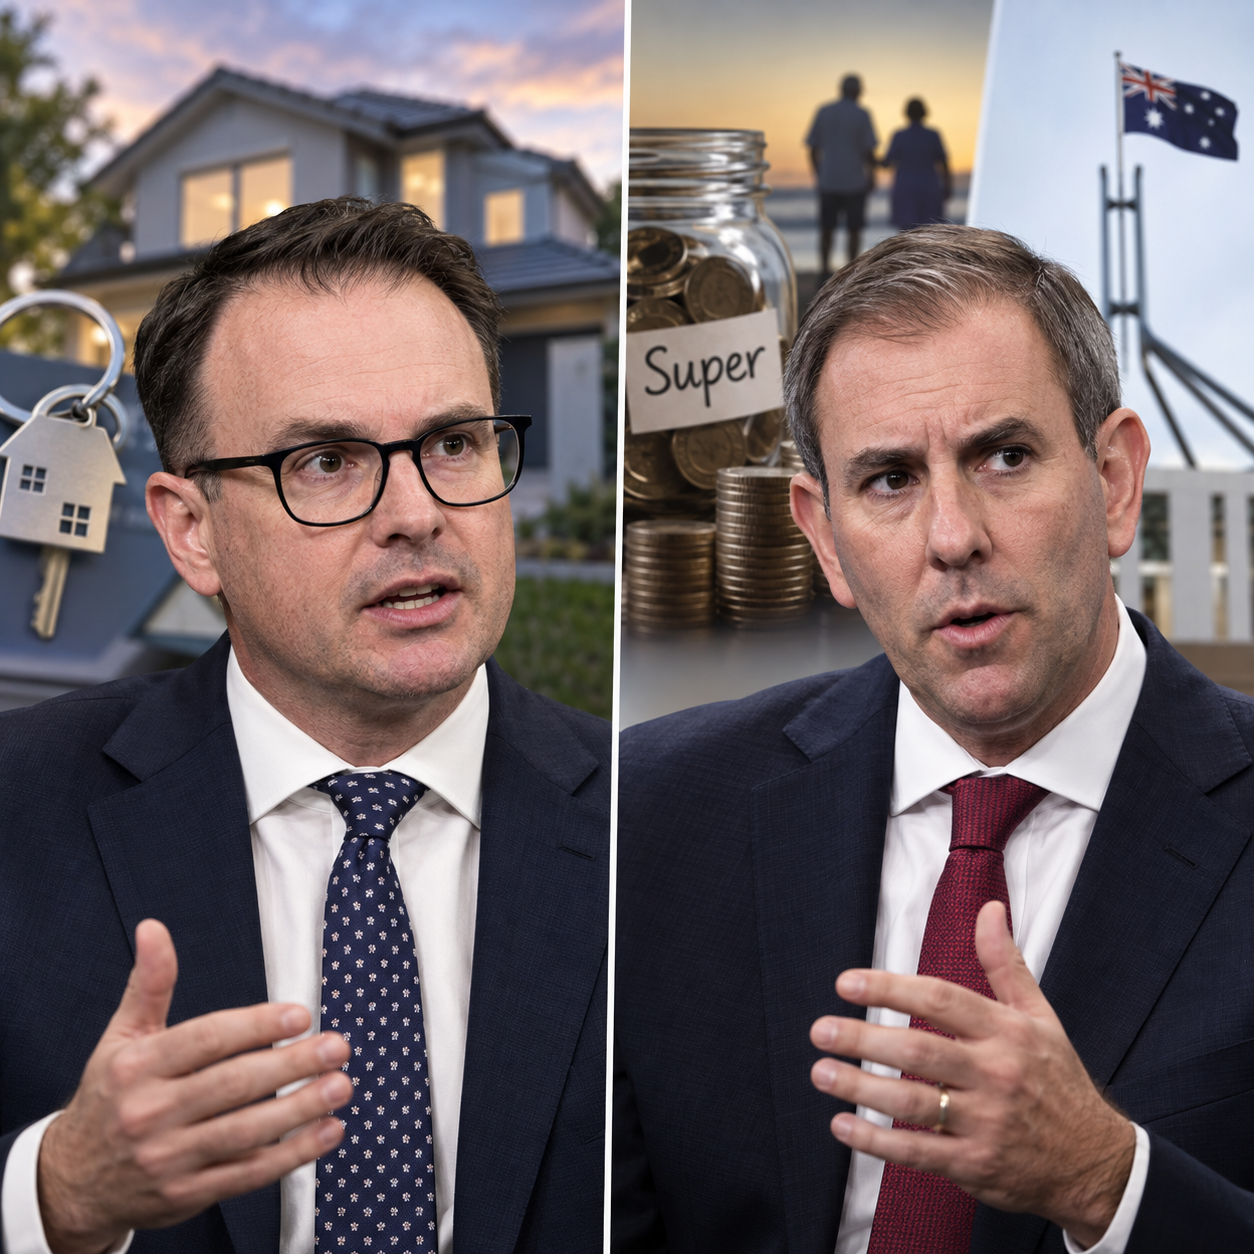
The Coalition has not announced a new policy. Bragg says the opposition is considering ideas and wants a national conversation about the relationship between home ownership and retirement security. Among the options he has raised are allowing super to be used as collateral for a home loan, withdrawing a lump sum for a deposit, or using retirement savings to reduce a mortgage.
That is an important qualification. The ideas are being debated inside and around the Coalition, but they have not been adopted as formal opposition policy. Bragg has said he is not yet advocating one particular model and that the purpose of his current intervention is to test options.
What is being floated?
One option would keep the money inside the superannuation system while allowing it to support a home loan as collateral or an offset. That could, in theory, help a borrower satisfy a lender without immediately withdrawing the retirement savings. Another option would permit a direct withdrawal for a first-home deposit. A third would allow super to be used later to reduce an existing mortgage.
Bragg argues that owning a home can itself be an important part of retirement security. He has said Australia should avoid a future in which renting in retirement becomes normal for people who would prefer to own. His broader point is that retirement policy should consider both financial assets and housing, because retirees who own their home generally face a different cost structure from those who continue paying market rent.
The Coalition went to the last two federal elections with a policy that would have allowed eligible first-home buyers to withdraw up to $50,000 from super for a deposit. Bragg has acknowledged a criticism of that model: younger people may not have accumulated enough super for the measure to help them, meaning the benefit could be concentrated among people in their 30s who already have larger balances.
Labor already operates a different mechanism, the First Home Super Saver Scheme. It allows people to make voluntary contributions into super, receive the tax treatment available to eligible super contributions, and later withdraw eligible amounts for a first-home deposit. The scheme does not generally allow people to tap compulsory employer super contributions for the same purpose.
The renewed debate has also been influenced by One Nation’s separate proposal to let people temporarily keep part of the income that would otherwise be paid into super and use it for rent or mortgage costs. ABC reporting says that proposal would allow three percentage points of salary to be redirected for up to three years. For a worker earning about $90,500, the party’s example equates to about $2,300 a year, or $44 a week.
Why do the two sides disagree?
The central disagreement is about what problem superannuation is supposed to solve. Labor argues that compulsory super exists to provide income in retirement and that weakening preservation rules risks leaving people with smaller balances later in life. Chalmers has described proposals to pull money away from super as damaging to retirement incomes and has argued that super should remain focused on retirement.
Bragg and other Coalition figures argue that home ownership can be just as important to retirement outcomes. Shadow Treasurer Tim Wilson has said people who reach retirement without owning a home face a much higher risk of financial hardship, and he argues that housing should therefore be treated as part of retirement policy rather than as a completely separate issue.
Both arguments identify a real trade-off. Money removed from super earlier in life is money that no longer compounds inside the retirement system. The effect can become large over decades. On the other hand, buying a home earlier can reduce exposure to rising rents and may allow a household to enter retirement with lower housing costs. The balance depends on house prices, investment returns, mortgage costs, age, income and the design of the policy.
There is also a housing-market question. If a policy increases the amount buyers can spend without increasing the supply of homes, some of the extra purchasing power can feed into prices. That risk is often raised by critics of demand-side housing assistance. The size of any effect would depend on how broad the scheme was, who qualified and whether additional housing supply reached the market at the same time.
Bragg’s collateral idea is different from a simple withdrawal and would need separate modelling. Keeping money invested in super while using it to support a mortgage could preserve some long-term investment exposure, but it would also create questions about what happens if the borrower defaults, how lenders value the collateral, whether the super fund carries any risk and what protections apply to retirement savings.
A mortgage-offset model would raise another set of technical questions. It could reduce interest costs without necessarily transferring ownership of the super asset, but the rules would have to determine who can access the arrangement, how much can be committed and what happens if a person changes jobs, funds or properties.
A direct withdrawal is easier to understand but creates a clearer reduction in the super balance. Supporters argue that the money is being moved from one long-term asset — super — into another — housing. Critics respond that residential property and diversified super investments play different roles and that not every home purchase will deliver the same financial outcome.
The debate also reflects changing housing conditions. More Australians are buying later, mortgage sizes have increased, and a growing number of people are approaching retirement while still renting or carrying debt. Those trends make the relationship between housing and retirement harder to ignore, even for policymakers who disagree about whether super should be part of the solution.
What changes now?
For the moment, nothing changes for super fund members because the Coalition has not announced a policy and the government has not altered the existing rules. Bragg’s speech is part of a policy debate, not a new entitlement that people can access today.
Anyone planning to buy a first home should therefore rely on the rules currently in force, including the existing First Home Super Saver Scheme where eligible, rather than assume compulsory super will soon become available for a deposit or mortgage. Financial decisions based on a proposal that may never become law carry obvious risks.
The next step for the Coalition would be to choose whether any of the options becomes formal policy, then publish enough detail for modelling. Key questions would include eligibility, caps, treatment of investment gains, safeguards against price inflation, interaction with lenders and whether any withdrawn amount must be repaid to super when a property is sold.
Labor is likely to continue arguing that the preservation of compulsory super is a core retirement principle. The Coalition, if it proceeds, will need to demonstrate that a housing-based model improves overall retirement security rather than simply shifting money from one asset class to another.
Policy design would also have to deal with distributional effects. A person with a large super balance may be able to use a housing-linked concession much more effectively than a younger worker with little accumulated super. Bragg has acknowledged that this was a credible criticism of the Coalition’s previous $50,000 withdrawal policy.
There would also be tax and administrative questions. Super receives concessional treatment because it is preserved for retirement. If compulsory savings can be pledged, withdrawn or redirected toward housing, lawmakers would need to decide whether the same concessions apply, what happens after a property sale, and whether people can rebuild the balance later.
Those details are why the current proposal is best understood as a policy discussion rather than an imminent rule change. Until the Coalition settles a model and publishes parameters, claims about who would gain, how house prices would respond or what the long-term retirement impact would be remain uncertain.
Even if the Coalition later chooses one of these models, legislation would be needed before compulsory super could be used under new rules. The eventual policy would also have to specify eligibility and safeguards. Until then, Bragg’s options remain a proposal for debate, not a change Australians can act on today.
For households, the argument is ultimately about two forms of long-term security: having enough financial assets to fund retirement and having stable housing costs later in life. Bragg’s intervention has reopened the question of whether policy should allow those goals to overlap more directly. The political debate is now live, but the practical rules have not yet changed.