More than three million Australians aged 65 and over are set to pay hundreds of dollars more each year for private health insurance under one of the Albanese Government’s most controversial health funding reforms, triggering a fierce political battle over fairness, aged care and the future pressure on the nation’s public hospital system.
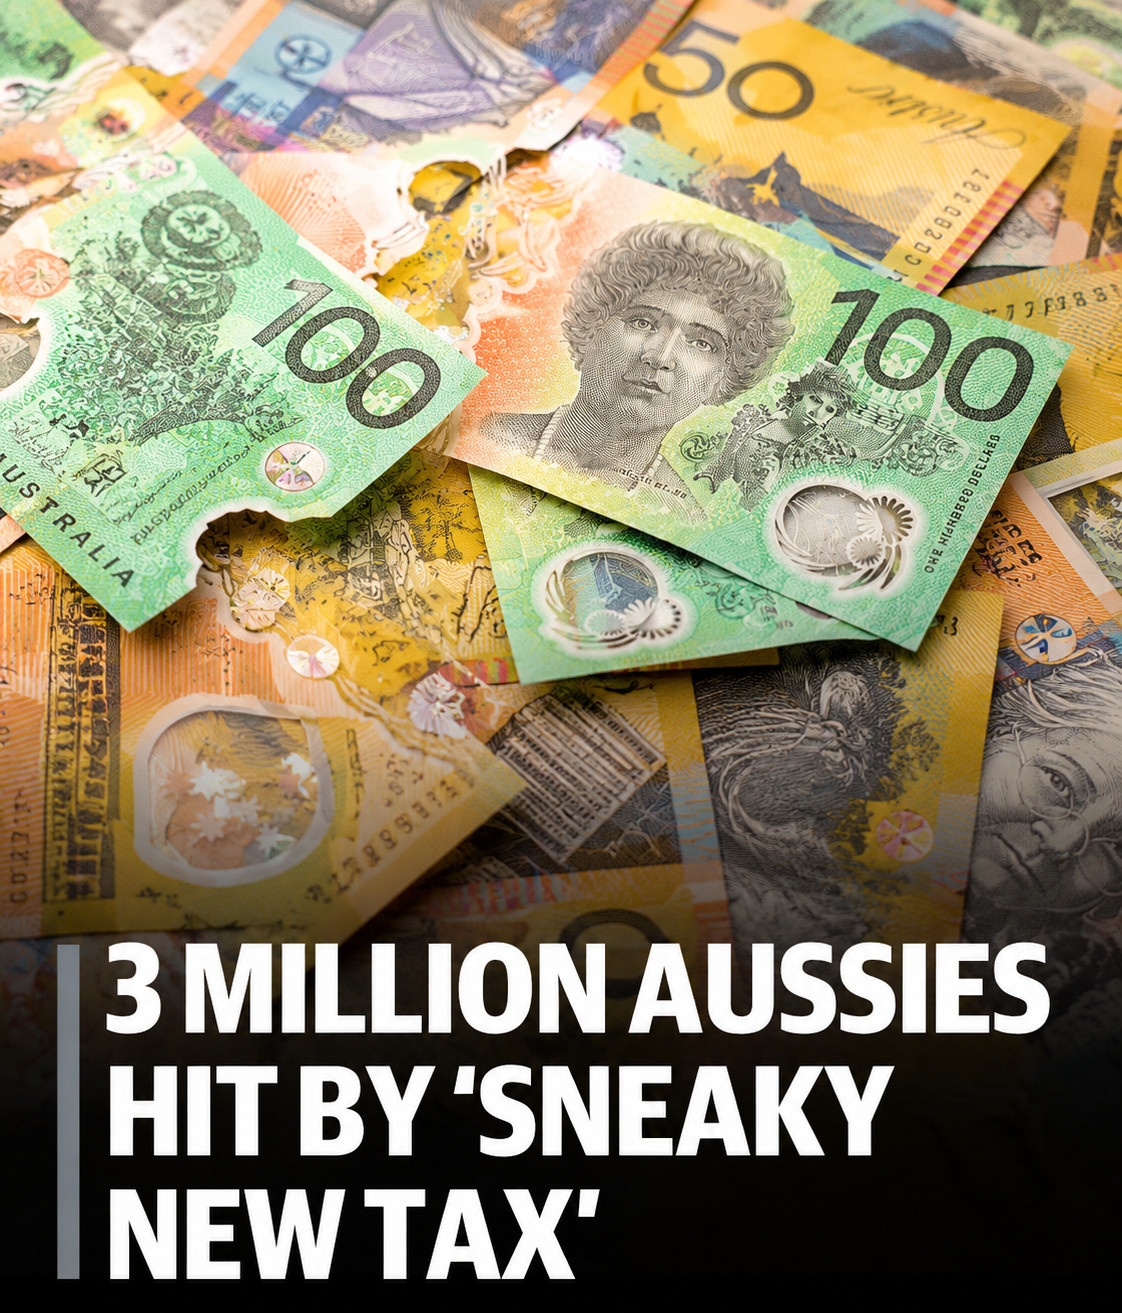
The proposed reform would abolish the higher age-based private health insurance rebate currently available to Australians aged 65 and over, replacing it with a single income-tested rebate regardless of age.
Under the changes, older Australians would receive the same rebate as younger households with similar incomes rather than the enhanced subsidy introduced by the Howard Government more than two decades ago.
Health Minister Mark Butler has defended the proposal as a necessary budget measure that restores what he describes as “intergenerational equity”.
The government estimates the reform will save around $3 billion over four years, with every dollar redirected into expanding aged care services, including additional residential aged care places and home care packages.
Speaking after announcing the policy, Butler acknowledged the decision was difficult but argued governments could no longer afford age-based subsidies when funding pressures in aged care continue to grow.
He said taxpayers should provide the same level of support to households on comparable incomes regardless of whether they were in their 50s or their late 60s and 70s.
“We have to find more money for aged care services,” Butler said, adding there was “no lazy free money lying around” and difficult budget decisions were unavoidable.
The government argues that the reform simply returns the rebate to an income-based system.
Older Australians will continue receiving a private health insurance rebate if they qualify under the income thresholds, but they will no longer receive additional assistance solely because of their age.
For many retirees, however, the financial impact could be significant.
Government estimates suggest Australians aged over 65 could pay roughly $240 to $250 more each year for their health insurance, while some people over 70 with more comprehensive policies could face substantially larger increases depending on their level of cover.
Private Healthcare Australia and other industry groups have warned that the increase may encourage thousands of older Australians to abandon private cover altogether.
Government modelling predicts approximately 44,000 policyholders could leave the private system after the changes take effect, although insurers argue the number may ultimately be considerably higher.
Those concerns have become a major focus of criticism from the federal Coalition.
Shadow Finance Minister Jane Hume described the proposal as a “tricky and sneaky” new tax on older Australians, arguing retirees who had maintained private cover for decades were now being unfairly penalised.
She said many seniors living on fixed incomes could be forced either to return to work or give up their private health insurance because they could no longer afford rising premiums.
According to Hume, removing incentives for older Australians to remain in the private system risks creating unintended consequences for the wider healthcare sector.
If significant numbers of retirees cancel their cover, she argues they will increasingly rely on already stretched public hospitals, leading to longer waiting lists and greater pressure on emergency departments.
She described the proposal as a “false economy” that could ultimately cost taxpayers more than it saves.
Those concerns are not limited to the federal opposition.
Health ministers in New South Wales, Queensland and Tasmania have reportedly expressed reservations about the reform, warning that any substantial movement of older patients from private hospitals into the public system could significantly increase demand for hospital services already under pressure.
Several state governments have reportedly urged Canberra to reconsider the proposal before implementation.
The private health insurance industry has mounted an extensive campaign against the changes.
Private Healthcare Australia argues older Australians currently use private hospitals far more frequently than younger people because healthcare needs naturally increase with age.
Industry representatives contend that maintaining stronger incentives for seniors ultimately saves taxpayers money by reducing demand on Medicare-funded hospitals.
Some modelling commissioned by the industry suggests certain retirees with comprehensive policies could eventually face premium increases substantially above the government’s average estimate once annual premium rises are also taken into account.
Advocacy groups have particularly raised concerns for lower-income pensioners who may struggle to absorb higher costs while already facing increasing living expenses.
Not all health policy experts agree that the consequences will be severe.
Some economists argue the government estimate of around 44,000 people leaving private cover is relatively modest when spread across Australia’s healthcare system.
They also note that the original age-based rebate introduced in the early 2000s appeared to have only a limited effect on encouraging additional private health insurance participation, suggesting its removal may likewise have only a moderate behavioural impact.
The proposed legislation would take effect from 1 April 2027 if passed by Parliament.
It would remove the additional rebate percentages currently available to people aged 65 to 69 and those aged 70 and over while retaining income testing for all policyholders.
The debate highlights broader questions facing Australia’s healthcare system as the population ages.
Successive governments have been forced to balance growing expenditure on hospitals, Medicare and aged care against increasing budget pressures.
The Albanese Government argues redirecting rebate savings into aged care better reflects where demand is growing fastest as Australia’s population continues to age.
Critics, however, believe weakening incentives for seniors to retain private insurance risks shifting costs rather than reducing them.
They argue every older Australian who leaves the private system increases demand for publicly funded healthcare, potentially offsetting much of the anticipated budget saving through higher hospital expenditure in future years.
Whether that prediction proves accurate remains uncertain.
The government’s modelling, private industry forecasts and independent expert assessments differ over the likely behavioural response of older Australians, ensuring the proposal will remain one of the most closely scrutinised health policy debates before the legislation reaches Parliament.
As political arguments continue, millions of retirees will be watching closely.
For many, the question is not simply whether they will pay an additional $250 a year, but whether Australia’s long-standing balance between private and public healthcare can be maintained while meeting the rapidly increasing demands of an ageing population.