Australia’s residential property market has suffered an estimated $230 billion decline in value over the past four months, intensifying political and economic debate over whether the Albanese Government’s housing policies are contributing to a broader slowdown in one of the nation’s most important sectors.
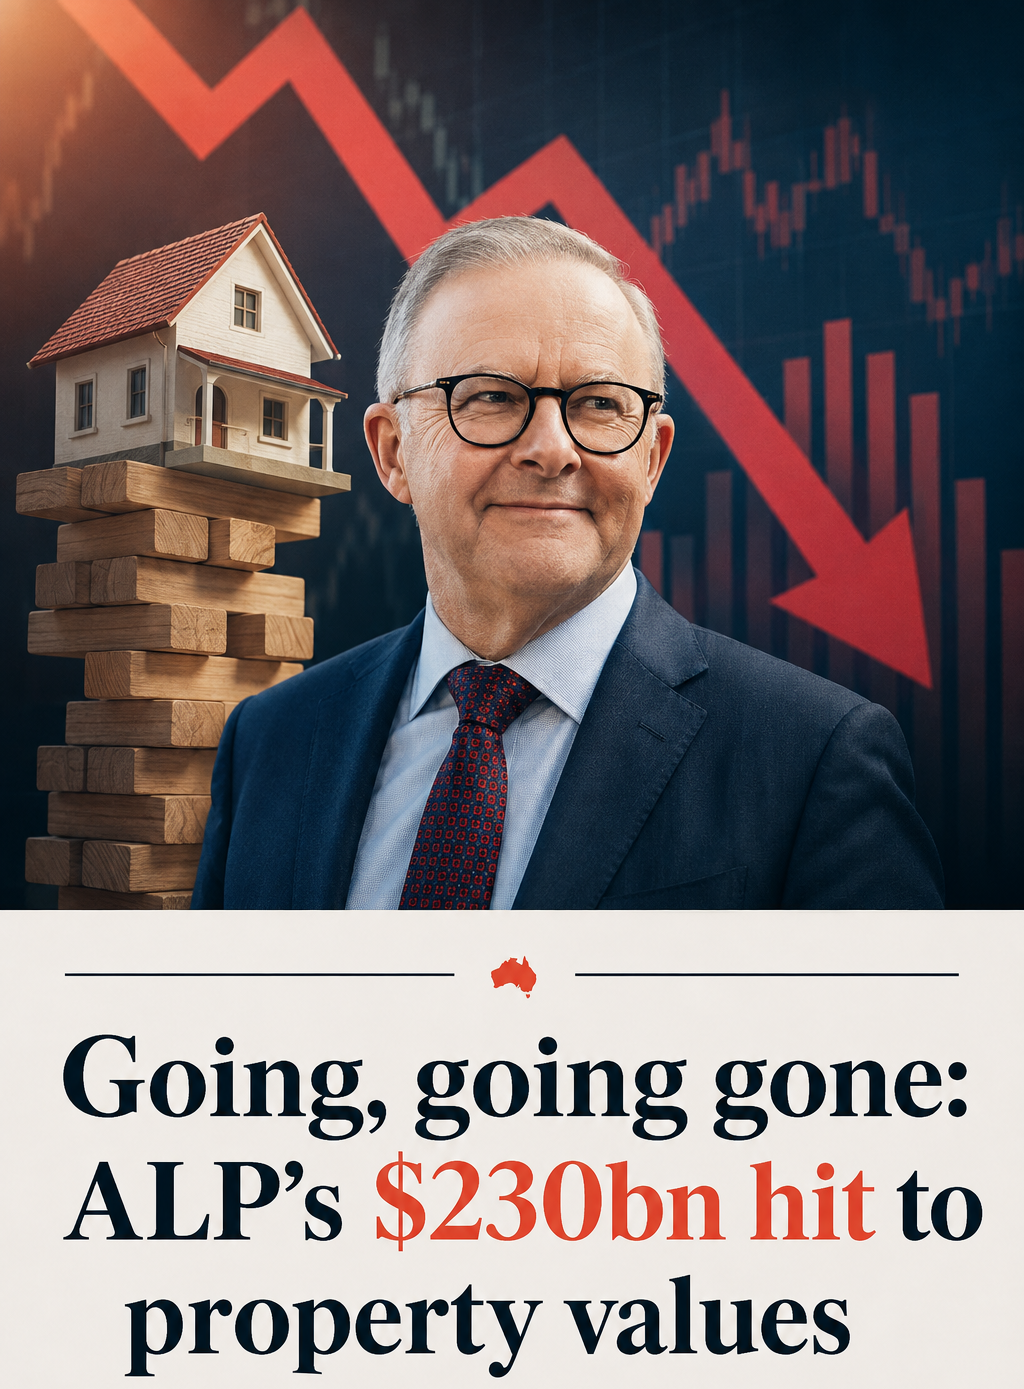
Recent market estimates suggest the total value of Australia’s housing stock has fallen from approximately $12.77 trillion in March to around $12.54 trillion, representing a decline of roughly $230 billion. The downturn follows several months of weakening house prices, softer auction clearance rates and slowing buyer activity across many of the country’s largest cities.
The latest figures have prompted criticism from sections of the property industry, with developer Tim Gurner arguing that recent federal policy changes have created a “sentiment of fear” among investors and developers at a time when Australia is already struggling with a chronic housing shortage.
According to Gurner, uncertainty surrounding tax reforms, investor confidence and broader government intervention has discouraged new projects, potentially worsening the nation’s long-term housing supply problems.
The property market has become one of the most closely watched parts of the Australian economy because housing represents the largest source of household wealth for millions of Australians. Even relatively modest price movements can influence consumer confidence, borrowing activity, construction investment and government revenue.
The recent downturn has been most noticeable in higher-priced metropolitan markets, particularly Sydney and Melbourne, although softer conditions have gradually spread into parts of Brisbane and other capital cities. More affordable regional markets have generally proven more resilient, reflecting stronger underlying demand and lower entry prices.
Several factors are contributing to the cooling market.
Higher interest rates have significantly increased mortgage repayments for borrowers, reducing borrowing capacity and limiting how much prospective buyers can afford to spend. At the same time, investor confidence has been affected by changes to housing-related tax settings and broader uncertainty surrounding future policy direction.
Critics of the Albanese Government argue these policy settings have accelerated the market slowdown by making residential property investment less attractive.
Among the most debated measures are reforms affecting investment incentives, including changes relating to negative gearing and capital gains tax arrangements, alongside expanded assistance for first-home buyers. Opponents argue the combined effect has distorted market behaviour while doing little to address the fundamental shortage of new housing.
The government, however, rejects suggestions that its housing agenda is responsible for the market correction.
Labor maintains that increasing housing supply remains the central objective of its reforms and has repeatedly pointed to its broader housing package, including the long-term target of delivering 1.2 million new homes nationwide. The government argues previous governments failed to adequately address structural supply shortages that developed over many years.
Housing affordability continues to dominate political debate because Australia faces both high purchase prices and historically tight rental markets.
Vacancy rates remain extremely low in many parts of the country, while population growth has continued to place additional pressure on available housing stock.
Many economists argue that Australia’s underlying housing shortage cannot be solved solely through tax policy. Instead, they point to planning regulations, infrastructure constraints, labour shortages and construction costs as major barriers to increasing supply.
Developers have also warned that uncertainty itself can discourage investment decisions.
Large residential projects often require years of planning, financing and regulatory approvals before construction begins. If developers become less confident about future demand or profitability, fewer projects may proceed, potentially reducing future housing supply and placing renewed upward pressure on prices once demand recovers.
The recent decline in property values has also revived concerns about negative equity.
Industry analysis suggests some recent first-home buyers who entered the market with relatively small deposits could now owe more on their mortgage than their property’s current market value. While negative equity does not automatically create financial distress, it can become problematic if homeowners need to sell during a downturn or experience unemployment.
Financial institutions continue to monitor the market closely, although Australia’s banking system remains well capitalised and mortgage arrears remain comparatively low by historical standards.
Many analysts believe the current correction differs significantly from previous housing downturns because employment levels remain relatively strong and widespread forced selling has not yet emerged.
Some economists have described the current weakness as a necessary adjustment following several years of exceptionally rapid price growth during and immediately after the COVID-19 pandemic. From this perspective, a moderation in prices could eventually improve affordability for prospective buyers, provided housing construction accelerates sufficiently to meet demand.
Others remain concerned that falling prices combined with reduced investor activity could discourage new residential construction precisely when Australia needs substantially more homes.
The building industry has repeatedly warned that construction costs, labour shortages and financing challenges continue to affect project viability across many parts of the country.
These challenges also raise questions about whether Australia’s target of building 1.2 million new homes over five years can be achieved within the planned timeframe.
Recent housing approval figures indicate construction activity remains below the pace required to meet that national objective, reinforcing concerns that supply may remain constrained even if demand weakens temporarily.
The political debate is therefore increasingly focused on balancing two competing priorities.
On one hand, policymakers want to improve affordability and expand home ownership opportunities, particularly for younger Australians who have struggled to enter the market. On the other, governments must avoid undermining investment confidence to the extent that fewer homes are built, potentially worsening shortages over the longer term.
For homeowners, investors, builders and prospective first-home buyers, the coming months will be closely watched for signs of whether the current decline represents a temporary correction or the beginning of a more prolonged adjustment.
While opinions remain divided over the precise causes of the recent downturn, there is broad agreement that Australia’s housing market remains central to the nation’s economic outlook and that resolving the country’s long-standing supply challenges will require sustained policy attention well beyond short-term movements in property prices.