A charity tennis match at The Lodge turned into an unusually public argument when Prime Minister Anthony Albanese and mortgage broker Joseph Daoud gave different accounts of the final score. Daoud, a critic of Labor’s housing tax changes, had paid $16,500 at a charity auction for the chance to face the prime minister. By the following morning, the two men were also facing off over what had happened on court.
Albanese told ABC News Breakfast that he had won 6-0, 6-0, 6-0. Daoud disputed that account, saying he had lost 6-0, 6-2. He claimed the more lopsided score had been circulated inaccurately. The difference might seem small for a fundraising event, but it immediately became a political talking point.
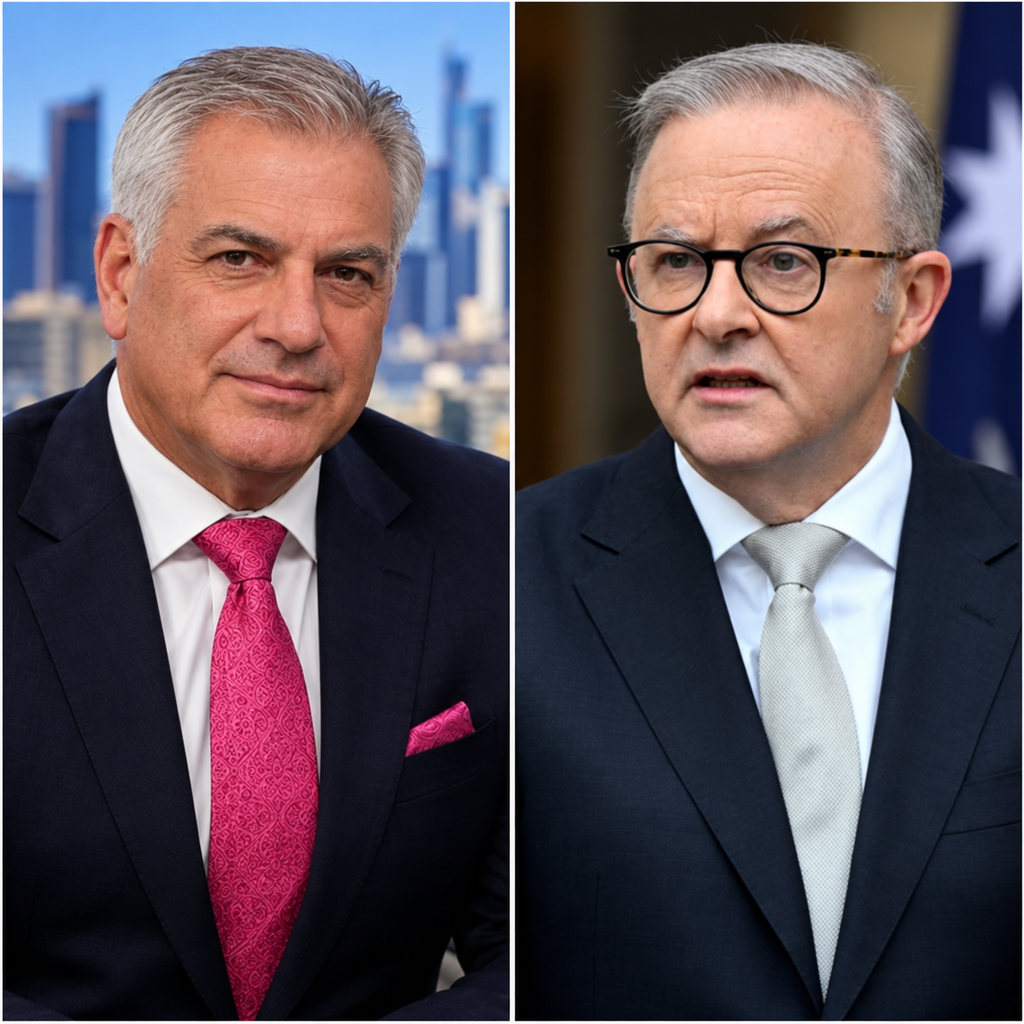
Daoud had secured the match through the Midwinter Ball charity auction, where his bid of $16,500 beat other offers. The invitation was unusual: a business owner who had been publicly critical of the prime minister’s policies would spend time competing against him on a tennis court. There was already a political disagreement before the first serve.
After the game, Daoud complained about the reported result and questioned aspects of how the match had unfolded. He also referred to an interruption in play. Crucially, he told the ABC he was not calling Albanese a cheater. His complaint was that the published account of the score did not match his recollection.
Albanese appeared pleased with the reported three-set victory. On television he repeated the 6-0, 6-0, 6-0 result, while stressing that the purpose of the match was to raise money. The prime minister also turned attention to Daoud’s advertising campaign against the government’s property tax changes, suggesting that money spent on billboards and skywriting could instead have gone towards charities such as St Vincent’s and Redkite.
That was a political answer as much as a sporting one. Daoud had used high-profile advertising to oppose housing tax changes, while the government argued its reforms would improve fairness and direct investment towards new homes. The two men disagreed over policy long before they disagreed over tennis.
The financial debate behind the match is far more consequential than the disputed score. The federal government’s announced tax package proposes changes to negative gearing for residential investment properties. It distinguishes protected existing holdings from certain later purchases of established investment homes. When the restrictions commence, affected investors would face limits on deducting rental losses against unrelated income, while qualifying new builds would retain broader negative-gearing treatment.
Treasury’s published explanation distinguishes purchases protected by transitional provisions from later acquisitions that would be subject to the proposed restrictions. Once the changes commence, investors acquiring affected established homes generally would not be able to use rental losses to offset unrelated income such as wages. They can instead apply losses against eligible residential property income or carry amounts forward under the proposed framework. Investors in qualifying new builds retain broader negative-gearing treatment. The practical outcome for any owner depends on the final law and the property concerned.
Consider two prospective buyers who earn the same salary and expect a rental property to run at a loss in its first year. If one buys a qualifying new dwelling and the other buys an established home affected by the restrictions, their after-tax cash flows may not be the same. The size of the difference would depend on the purchase price, mortgage interest, rent, expenses and each person’s taxable income. There is no single advertised saving that applies to every borrower. That is precisely why brokers and prospective investors are following the reform closely.
Capital gains tax is the other major piece of the debate. The government’s proposed tax package includes replacing the existing 50 per cent discount on eligible gains with an inflation-based calculation and a minimum tax on real gains, with different treatment available for eligible new builds. The proposed changes include transitional treatment intended to distinguish historical appreciation from gains affected by the new arrangements. Anyone contemplating selling an investment property needs to distinguish the gain accrued before the change from gains affected by the future arrangements.
Those reforms also explain why disputes over housing supply are unlikely to disappear. Supporters say channelling tax benefits towards new dwellings could encourage construction and improve the number of homes available. Critics argue that higher after-tax costs for some investors could discourage property investment or put pressure on rents. Those outcomes are predictions, not figures that can be read off a tennis scorecard. Borrowing costs, building approvals, interest rates and local vacancy rates will still matter.
The charity auction has its own tax distinction. The Australian Charities and Not-for-profits Commission notes that a normal tax-deductible gift involves no material benefit for the donor and that an organisation must hold deductible-gift-recipient status. The Australian Taxation Office also has specific rules and limited exceptions for some fundraising events. Buying a tennis experience through an auction is not automatically equivalent to giving money without receiving anything in return. The public account of Daoud’s bid does not establish whether any deduction was claimed.
For a borrower, the useful takeaway from the larger policy argument is to separate a headline about negative gearing from an actual financing decision. A loan repayment, land tax, maintenance, insurance, a vacancy period and the timing of an eventual sale can all change an investment’s cash flow. The federal reforms affect only part of that calculation, and state taxes can add another layer. The property dispute that brought Daoud to public attention is therefore more consequential than the lively disagreement over his afternoon on the court.
Investors comparing properties must also consider expenses that sit outside the federal tax debate. Council rates, landlord insurance, strata levies, repairs and vacant weeks can alter a property’s cash position even when the mortgage stays unchanged. A new build may involve a different maintenance profile from an older home, but neither age nor type guarantees a profitable investment. A useful financing calculation starts with the rent likely to be received and the full cost of ownership, rather than an assumed tax deduction.
The timing of a sale can matter as much as the timing of a purchase. The budget proposals on capital gains contain transitional considerations and a different option for qualifying newly built homes. An investor needs to know which arrangements apply to the property and what part of any gain falls within the relevant period. These are questions for the actual law and professional advice, not matters decided by who scored the most games in a charity tennis match.
Housing policy also has a public-facing dimension beyond investors’ returns. Some households are trying to enter the market, while tenants face the possibility of rising rent and scarce vacancies. More building activity may eventually ease a shortage, but construction is affected by financing, planning approvals and costs that tax policy alone cannot settle. This was the substantive dispute in the background when Daoud and Albanese met. Their disagreement over the result was colourful precisely because their differences about housing were already well known.
For a prospective investor, that distinction could change the numbers behind a purchase. The tax treatment of a rental loss is not the same as the interest rate on a mortgage, the amount of rent received or the eventual capital gain when the property is sold. A buyer considering an older dwelling and another considering a newly built property may need to model different cash-flow outcomes, depending on the acquisition date and their personal circumstances.
The rules have been politically contentious because investors, renters and first-home buyers experience the housing market differently. Labor says directing the tax concession towards new construction will encourage supply. Critics worry about effects on investor decisions and rental markets. Neither view can be settled by a charity match, and the eventual impact of the reforms will depend on the behaviour of buyers, builders and tenants over time.
The charity setting also raises a practical question: when is a fundraising payment tax-deductible? The Australian Taxation Office generally distinguishes a genuine donation from a purchase that provides a material benefit in return. Paying to receive something at an auction does not automatically count as a deductible gift just because proceeds go to a worthy cause. Some fundraising concessions have their own conditions. Nothing in the match reporting establishes how Daoud personally treated the payment for tax purposes.
The distinction between fundraising and tax deductions is easy to lose in a colourful political story. A bidder may be motivated by charity, an unusual experience, business promotion or several things at once. The amount paid is publicly reportable; the bidder’s tax return is not. There is no need to speculate about his personal finances to understand why the match attracted attention.
Nor is there a verified scorecard in the available ABC account that resolves the players’ conflicting recollections. Albanese maintained the clean sweep; Daoud insisted the match was closer. Both accounts can be reported without treating either man’s version as an independently established finding.
One reason the row travelled so widely is that it combined familiar political arguments with an unusually relatable setting. Anyone who has played a social match knows scores can become a source of pride. Few matches, though, involve a prime minister, a determined policy critic and a five-figure charity auction bid.
Whatever the score, the two men brought their existing housing-policy disagreement onto the court and then back into public view. The charity match raised money for a cause. Its disputed result became a reminder that even a friendly sporting contest can end in an argument when politics is already part of the occasion.






