An 81-year-old woman was pursued for months over an insurance debt she was not responsible for, in a case that has intensified scrutiny of the debt-collection practices used by major insurers and automated recovery systems.
Diane Walker was contacted by ARMA Group, a debt collector acting on behalf of Suncorp, after an insurance claim involving a vehicle. ABC News reported that she faced repeated demands and legal threats over a liability that Suncorp later abandoned because it did not have sufficient evidence to establish she was responsible.
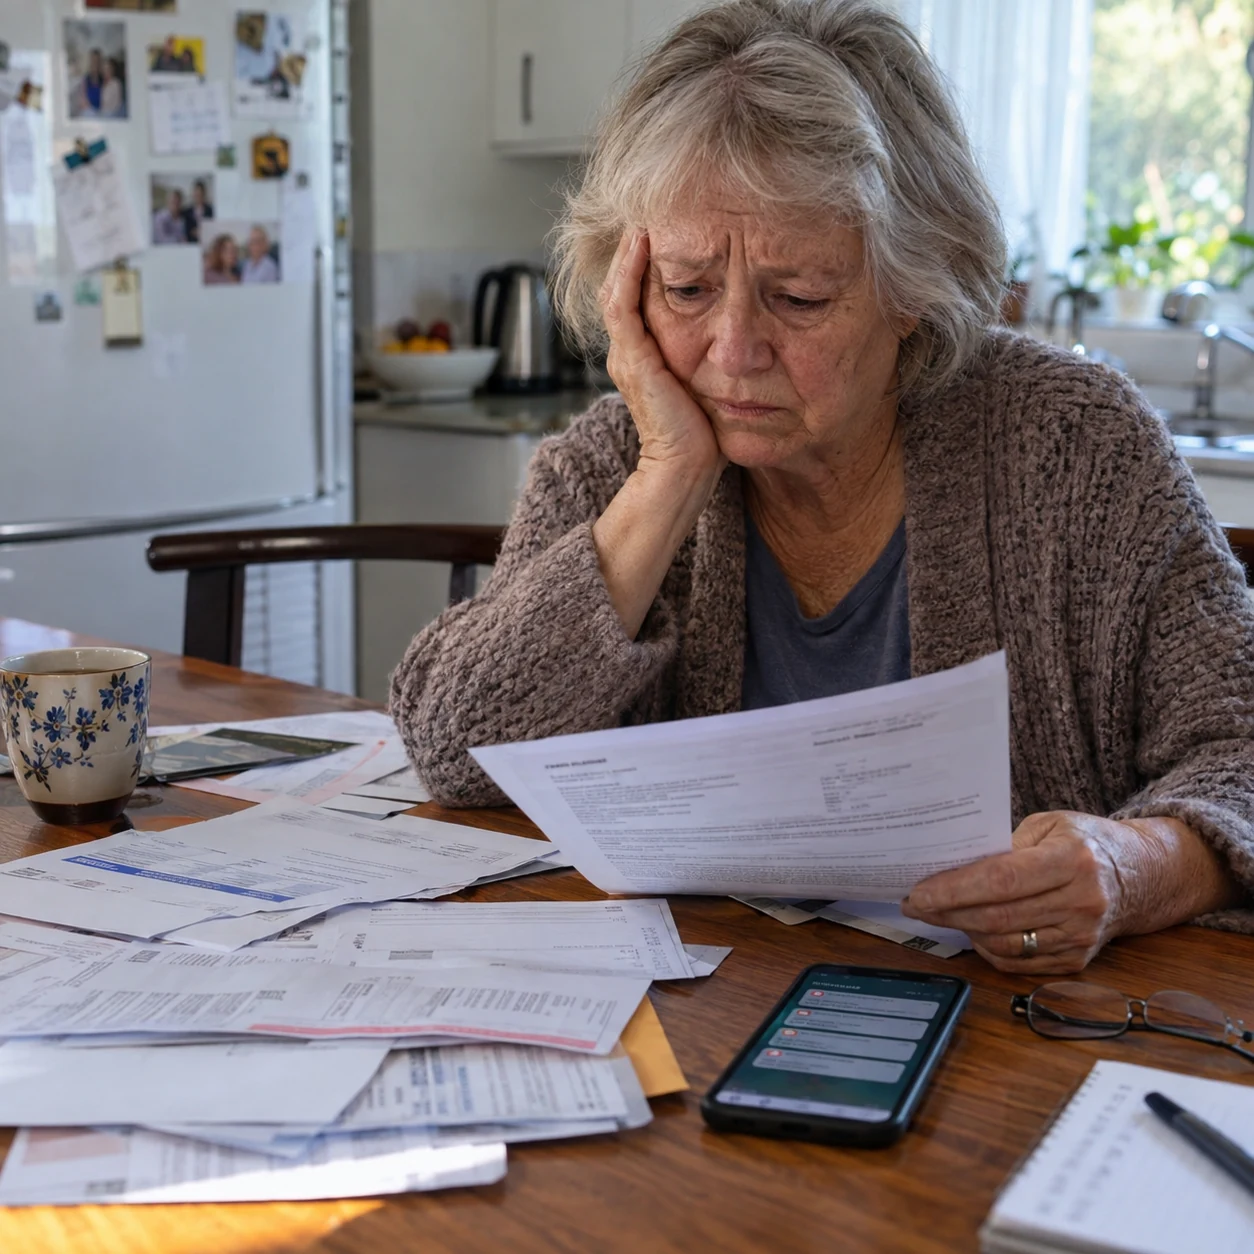
Suncorp eventually apologised and paid Ms Walker $1,500 as a goodwill payment after acknowledging that debt recovery had been engaged prematurely. The insurer also said it had taken formal disciplinary action with ARMA over the handling of the matter, while maintaining its commercial relationship with the collector.
ARMA has disputed the characterisation of its conduct and has said allegations made about its handling of Ms Walker’s case are unsubstantiated. The company says it is comfortable that it acted appropriately.
The disagreement does not change the central fact that the underlying claim was ultimately withdrawn. It raises a broader consumer question: what safeguards should exist before an insurer refers an individual — particularly an older person — to a debt collector armed with escalating letters, calls and the prospect of legal action?
Debt collection is a legitimate part of the financial system. Businesses are entitled to pursue debts that are genuinely owed, and insurers can seek recovery when they have evidence that another party is liable for a loss.
But the power imbalance can be substantial.
A debt-collection notice can look authoritative even when liability has not been tested in court. Many consumers do not have lawyers and may assume that a demand from a professional collection agency means the debt has already been legally established.
In Ms Walker’s case, her son became involved and challenged the claim. The dispute continued for months before the insurer withdrew it.
The case has attracted attention partly because it comes as ARMA is separately facing Federal Court proceedings brought by the Australian Competition and Consumer Commission.
Those proceedings are not about Ms Walker and should not be treated as proof of what occurred in her individual case.
The ACCC alleges that ARMA and Force Legal, businesses under common ownership, sent more than 320,000 debt-enforcement notices over about three and a half years that could mislead recipients about their legal position.
The regulator alleges some notices related to debts that were no longer outstanding or were statute-barred, and that some communications created a misleading impression about possible legal enforcement.
Those are allegations being tested in court. ARMA and Force Legal are entitled to respond, and no final finding should be assumed.
The scale of the ACCC case nevertheless shows why debt-collection communications matter.
A letter or text does more than request money. Its wording can influence whether a consumer pays, seeks advice, disputes liability or simply gives up because the process feels intimidating.
Australian consumer law and industry guidance place limits on how debts can be pursued. Collectors are expected to avoid undue harassment, coercion and misleading representations. They also need to be careful about contacting vulnerable consumers and about implying legal consequences that are not available.
The practical problem is that consumers often encounter those protections only after something has gone wrong.
An older person receiving repeated demands may not know which regulator to contact, whether the collector has the right person, whether the amount is correct or whether an insurer has enough evidence to establish liability.
The first step should be verification.
A consumer who disputes a debt can ask for information showing how the amount was calculated, why the collector believes the person is liable and who the original creditor is. If the issue involves an insurer, the insurer’s internal dispute-resolution process may also be relevant.
Where the dispute cannot be resolved directly, external complaint and legal pathways may be available depending on the type of debt and organisation involved.
Those options are easier to use when a person has support from family, a financial counsellor or a lawyer. They can be much harder for someone who is isolated, unwell or unfamiliar with digital communications.
That makes the conduct of the original creditor important as well as the conduct of the collection agency.
Outsourcing recovery does not remove an insurer’s responsibility to ensure the debt is sufficiently supported before escalation. If a claim is uncertain, sending it into a collection process can create stress that is difficult to undo even if the demand is later withdrawn.
Suncorp’s response in Ms Walker’s case recognises that point. The company said debt recovery should not have been engaged when it was and apologised for the impact.
It is also significant that Suncorp has not ended its relationship with ARMA. That suggests the insurer views the incident as a problem requiring remediation rather than as a reason to abandon the collector entirely.
For consumers, the broader issue is whether those remediation steps are strong enough to prevent similar cases.
Automated systems can make debt recovery faster and cheaper, but they can also amplify an error. Once a person is placed into a workflow of reminders, notices and escalation, each step can arrive automatically even when the original liability remains disputed.
Human review becomes most important precisely when the system is uncertain.
A wrong debt pursued efficiently is still a wrong debt.
That is the lesson from the Walker case and from the wider regulatory scrutiny now surrounding parts of the debt-collection industry.
The immediate dispute has ended: Suncorp withdrew the claim, apologised and paid a goodwill amount. The larger questions — how insurers verify liability before referral, how collection agencies handle disputed debts and how automated recovery is supervised — remain live for regulators, companies and consumers.