Clive Palmer’s bitter dispute with Jacqui Lambie became more than an internal argument over loyalty when the senator broke with her party’s position on changes to financial advice protections. Palmer branded Lambie a liar, while Lambie accused him of trying to intimidate her and insisted she would act independently in Parliament. The conflict exposed how a fractured crossbench party could influence the rules governing financial advice for ordinary Australians.
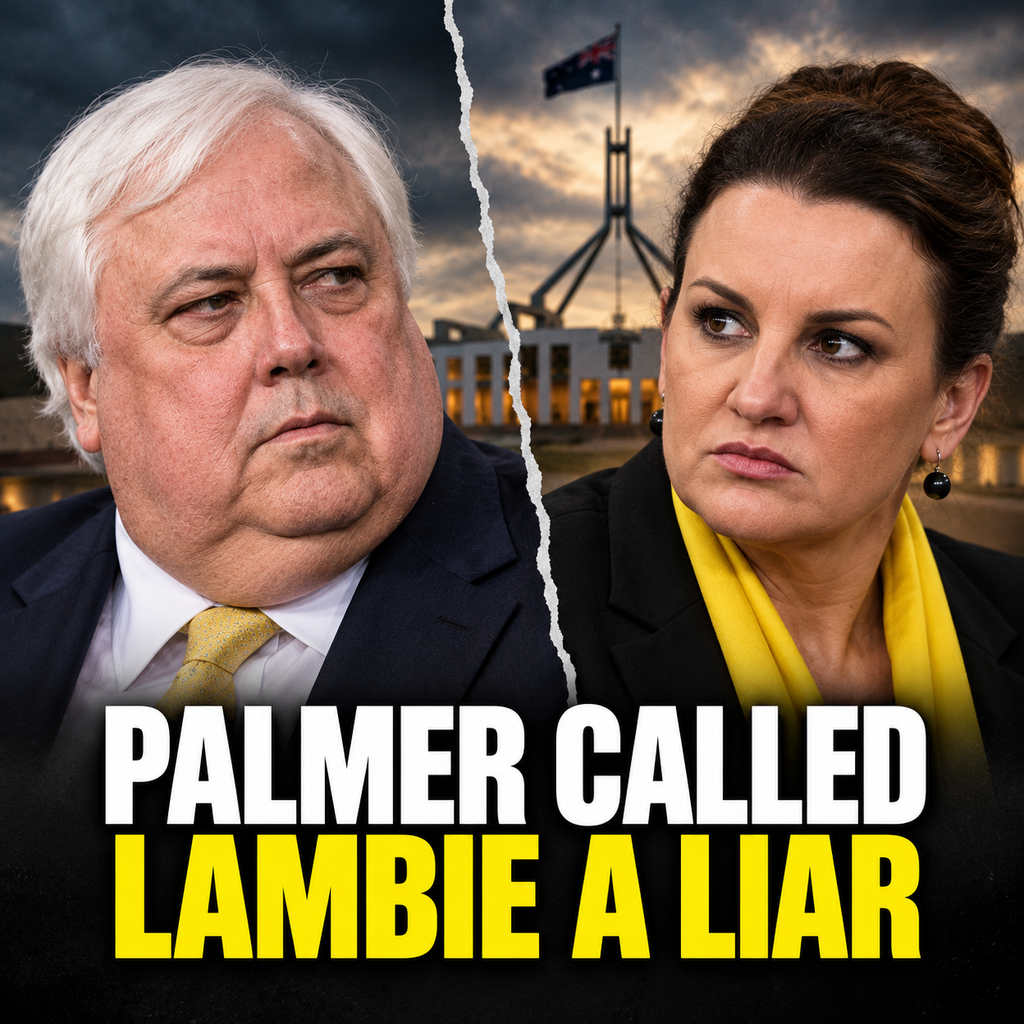
The confrontation was recorded in ABC reporting of the Palmer United Party’s internal breakdown. The accusation that Lambie had lied was Palmer’s claim, not a finding by a court or parliamentary inquiry. Equally, Lambie’s allegations about pressure and threats were her account of the political relationship. The established story is the exchange, the party’s disciplinary response and Lambie’s parliamentary voting position.
The immediate legislative issue involved changes to the Future of Financial Advice framework, commonly known as FOFA. These were not remote procedural questions. The framework addressed how financial advisers deal with retail clients and the conflicts that can arise when an adviser is remunerated by product providers or other parties. Whether protections were retained, weakened or reworked had potential consequences for people seeking advice about retirement savings, investments and other financial products.
According to ASIC, the original FOFA reforms included a duty for financial advisers to act in clients’ best interests, restrictions on conflicted remuneration and related obligations intended to strengthen consumer protection. Those measures formed the background to the parliamentary contest. The specific government changes being debated should not be conflated with the entire FOFA regime, nor should a single Senate vote be portrayed as eliminating every consumer protection or permanently resolving all future regulatory questions.
Lambie had initially supported the government’s proposed changes, but said she had become better informed and reversed her position. She joined Labor, the Greens and other crossbench senators to overturn the changes. The shift angered the Palmer United Party. The party stripped Lambie of her deputy leadership role in the Senate and suspended her from partyroom meetings. Those are documented political consequences, distinct from removal from Parliament itself.
Palmer issued a statement accusing Lambie of lying to the Senate and suggesting she needed help to get back on track. He also claimed she had stopped communicating with him and was planning to create an alternative party. Those were allegations put forward by Palmer and should not be represented as independent findings. Lambie said she would not be deterred by what she called abusive threats and argued that Palmer was seeking to interfere with her duty as a senator.
The disagreement had also involved defence force pay and Lambie’s determination to represent veterans. She had indicated she was prepared to vote against government legislation as part of her protest over proposed pay arrangements for Defence personnel. That issue helped explain why the dispute became a broad struggle over party discipline rather than an isolated disagreement over financial regulation. The veteran and consumer-protection arguments were distinct policy issues, connected through the senator’s willingness to break party ranks.
For voters, the most important institutional point is that a senator’s parliamentary vote belongs to the elected senator. Parties can impose internal sanctions and control positions within the party organisation, but removing someone from a party role is not the same as cancelling their mandate. A breakdown in party cohesion can make legislative outcomes less predictable, particularly when the government needs the votes of crossbench members.
The implications for financial services deserve attention because technical terms can obscure real consumer interests. Conflicted remuneration can create an incentive for an adviser or intermediary to recommend one financial product over another for reasons that are not aligned with a client’s needs. A best-interests obligation seeks to influence the standard of conduct expected when providing personal financial advice. Neither measure can guarantee good outcomes in every individual case, but they frame the duties and accountability of the advice industry.
Regulatory design involves trade-offs. Industry participants may argue that compliance obligations increase costs and make advice less accessible. Consumer advocates may argue that lowering obligations creates opportunities for unsuitable recommendations or hidden conflicts. Those propositions need evidence about costs, behaviour and outcomes. The existence of a political dispute is not proof that every adviser acted badly, just as the adoption of a consumer protection rule is not proof that mis-selling disappeared.
ASIC’s explanation of the FOFA measures provides a more useful foundation for assessing the debate than either politician’s insults. It identifies the best-interests duty and conflicted-remuneration restrictions as core features. Consumers comparing advice services can use those concepts to ask what services are being provided, how fees are calculated and what incentives may influence recommendations. This is general explanatory context, not personalised financial advice.
The Palmer–Lambie conflict also illustrates the tension between party discipline and constituency representation. Parties seek consistency so voters understand a platform and governments can negotiate reliable support. Independent-minded senators may argue that new information or local priorities justify a different vote. Both principles have democratic relevance. The political consequences become particularly visible when a party’s leader and a senator publicly accuse one another of dishonesty.
The language escalated because each side tried to claim legitimacy. Palmer framed the problem as Lambie’s conduct and reliability. Lambie framed it as her right to discharge parliamentary responsibilities free from intimidation. Neither framing should be accepted without attribution. A useful report instead identifies the measurable steps: the changed vote, the loss of party responsibilities and the public statements issued by each side.
Financial advice law can be complicated even for people who follow politics closely. Consumers may not distinguish a duty of loyalty from an obligation to provide a fee disclosure document, or a commission ban from broader restrictions on adviser conduct. The dispute shows why elected representatives should explain what a legislative change does, rather than leave the public to infer its meaning from a dramatic argument between party figures.
It also provides a warning about treating parliamentary arithmetic as an afterthought. Government proposals often depend on negotiations with senators whose positions can change as further information becomes available. When those senators come from small parties with their own internal tensions, the government may find that an apparent agreement does not produce a predictable vote. That procedural uncertainty can determine whether rules affecting consumers and businesses survive parliamentary scrutiny.
The story’s lasting significance is therefore twofold. On the surface it was a personal and bitter feud, with Palmer calling Lambie a liar and Lambie rejecting what she saw as intimidation. Beneath that conflict was a Senate decision about protections surrounding financial advice. The public record establishes the clash and the vote; it does not authorise journalists to repeat each politician’s personal allegations as fact. In this case, the legislative context explains why a war of words mattered beyond the personalities involved.
The government changes debated by the Senate were politically sensitive because financial advice can affect long-term savings that clients may not be able to replace. Fees and commissions can be difficult to compare, particularly where products differ in risk, liquidity and tax treatment. A client may not know whether an apparently straightforward recommendation carries a financial incentive for the person giving it. That is why policy makers have devoted attention to disclosure, duties of care and conflicts of interest. These safeguards are not a promise that investment markets will perform well; they are standards for the advice relationship.
ASIC’s description of FOFA also helps distinguish personal financial advice from general information. The obligations attached to a recommendation can depend on the service being provided and the client’s circumstances. A consumer reading about parliamentary reform should not infer that a single vote determines the quality of every interaction with a bank, broker or adviser. The relevant duties, the type of advice and the regulatory setting all matter. For readers, the larger issue is transparency about who benefits from a recommendation and who bears its risks.
The crossbench setting gave Lambie’s decision a significance disproportionate to the size of the Palmer United Party. When a government does not have assured support for every proposal in the Senate, a small number of legislators can determine whether a regulatory amendment survives. Their votes can create immediate consequences for the legal framework, even though voters may be more familiar with disputes among party leaders. The ABC’s report links Lambie’s position to the reversal of the government’s changes, making the legislative outcome a central fact rather than an incidental detail.
It would also be unfair to treat a changed parliamentary position as proof of either bravery or dishonesty without examining the explanation. Lambie said she had reconsidered the measures with more information. Palmer challenged her credibility and party loyalty. Those competing interpretations are political claims. The verifiable actions are that she altered her vote, the party imposed internal consequences and Parliament acted on the financial advice changes. Those actions give readers a grounded basis for judging the dispute without adopting either personal attack as fact.
Financial regulation also shows why the substance of a Senate vote deserves more attention than factional insults. Households may base irreversible savings decisions on professional advice, while advisers work within changing legal obligations. The rules deserve careful public explanation on their own terms. The Palmer–Lambie dispute helps illuminate the politics of those rules, but cannot replace an assessment of the underlying consumer protections.