Millions of older Australians are set to lose access to higher age-based private health insurance rebates from April 2027 under a major federal government overhaul that will instead determine rebates solely according to income.
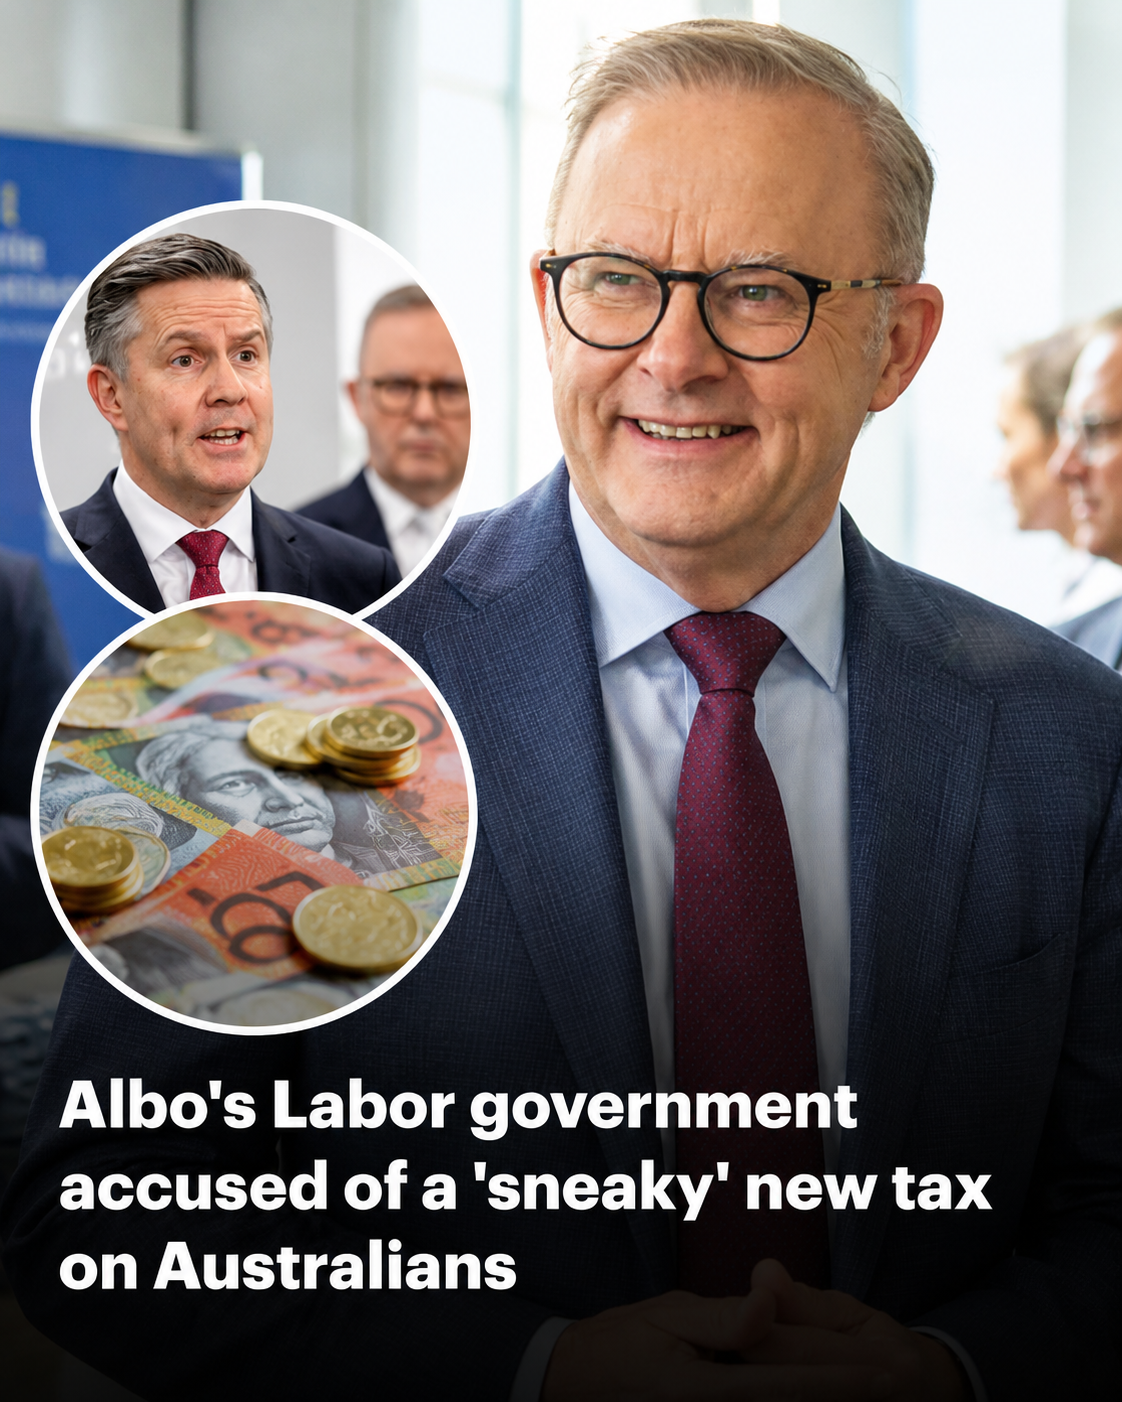
The reform, announced by Health Minister Mark Butler ahead of the May federal Budget, will abolish the long-standing system under which Australians aged 65 and over receive larger government rebates than younger people on the same income. From April 2027, people with identical incomes will receive the same rebate regardless of their age.
Under the current arrangements, Australians aged 65 to 69 receive a higher rebate than younger policyholders, while those aged 70 and over receive an even larger subsidy to help offset the cost of private health insurance premiums.
Once the new system takes effect, those additional age-based rebates will disappear.
Government estimates indicate around three million Australians could be affected. Depending on age and the level of cover held, some people aged over 65 may pay up to A$250 more each year, while some people aged over 70 could face increases of up to A$500 annually.
For example, under the existing system, a 72-year-old and a 45-year-old with the same taxable income receive different rebate rates because of the age loading. From April 2027, both policyholders will receive identical government assistance if they fall within the same income tier.
The Albanese government argues the reform is designed to improve intergenerational fairness.
Health Minister Mark Butler has said the rebate should reflect a person’s capacity to pay rather than their age, arguing Australians on the same income should receive the same level of government support. He has also said the savings generated by the reform will be redirected into strengthening Australia’s aged care system as demand continues to increase with an ageing population.
Butler has defended the policy as one of several difficult fiscal decisions required to balance growing healthcare and aged care costs.
“Income—not age—should determine the level of taxpayer support,” the government has argued, saying the reform better targets public funding while preserving rebates for lower-income Australians.
The announcement has triggered strong political opposition.
Liberal deputy leader Jane Hume described the measure as “profoundly unfair”, accusing Labor of breaking an election commitment and imposing what she characterised as a multibillion-dollar tax increase on older Australians.
Opposition Leader Angus Taylor likewise criticised the policy, arguing it would encourage some retirees to abandon private health insurance and place additional pressure on already stretched public hospitals operated by the states.
Several state governments have also raised concerns.
Health ministers in New South Wales, Queensland and Tasmania have warned that if significant numbers of older Australians cancel their private cover because of higher premiums, demand for elective surgery, emergency care and hospital admissions could increasingly shift onto the public health system.
Consumer groups and organisations representing older Australians have expressed similar concerns.
Some argue retirees often maintain private health insurance despite living on fixed incomes because it provides faster access to elective procedures and specialist care. They warn that additional annual costs could force some households to reconsider whether they can continue paying premiums.
Recent reporting has highlighted examples of retirees who say they regard private health insurance as essential after receiving timely cancer treatment or surgery through the private system, but now fear the higher costs may force difficult financial choices.
The government, however, disputes suggestions that large numbers of people will abandon private cover.
Officials maintain that income-tested rebates will remain available and that the savings generated by the reform will improve aged care services, including additional home care packages and support for an ageing population.
The private health insurance rebate has been part of Australia’s health funding system since 1999.
Originally introduced by the Howard government, the rebate was designed to encourage Australians to purchase private health insurance and reduce pressure on the public hospital system. It was later modified so that both income and age influenced the rebate received by each policyholder.
Australia’s healthcare system operates through a combination of Medicare-funded public healthcare and a substantial private health insurance sector.
People with private cover often receive faster access to elective procedures, greater choice of doctor and treatment in private hospitals, while Medicare continues to provide universal access to public hospital services and many medical benefits. Governments of both major parties have traditionally supported maintaining a strong private sector alongside the public system to reduce demand on publicly funded hospitals.
Economists remain divided over the likely consequences of removing the age-based rebate.
Some argue that directing assistance according to income rather than age represents a fairer use of taxpayer funds, particularly where higher-income retirees continue to receive larger subsidies simply because of their age.
Others contend older Australians generally make greater use of healthcare services and therefore have stronger incentives to maintain private insurance. They warn that reducing financial support could ultimately increase costs elsewhere if more patients move into the public hospital system.
The debate also reflects broader fiscal pressures facing the Commonwealth.
Australia’s population continues to age, increasing expenditure on aged care, health services and pensions. Governments are increasingly required to balance those growing costs against competing budget priorities while attempting to maintain affordable access to healthcare.
Although the policy has become politically contentious, the legislation implementing the change means the higher age-based rebates are scheduled to end from April 2027 unless a future Parliament amends or repeals the reform.
For older Australians with private health insurance, the coming months are likely to involve careful consideration of future premium costs, rebate entitlements and the value of maintaining private cover. For governments, the policy will become an important test of whether changing rebate eligibility improves budget sustainability without significantly increasing pressure on Australia’s public hospital system.