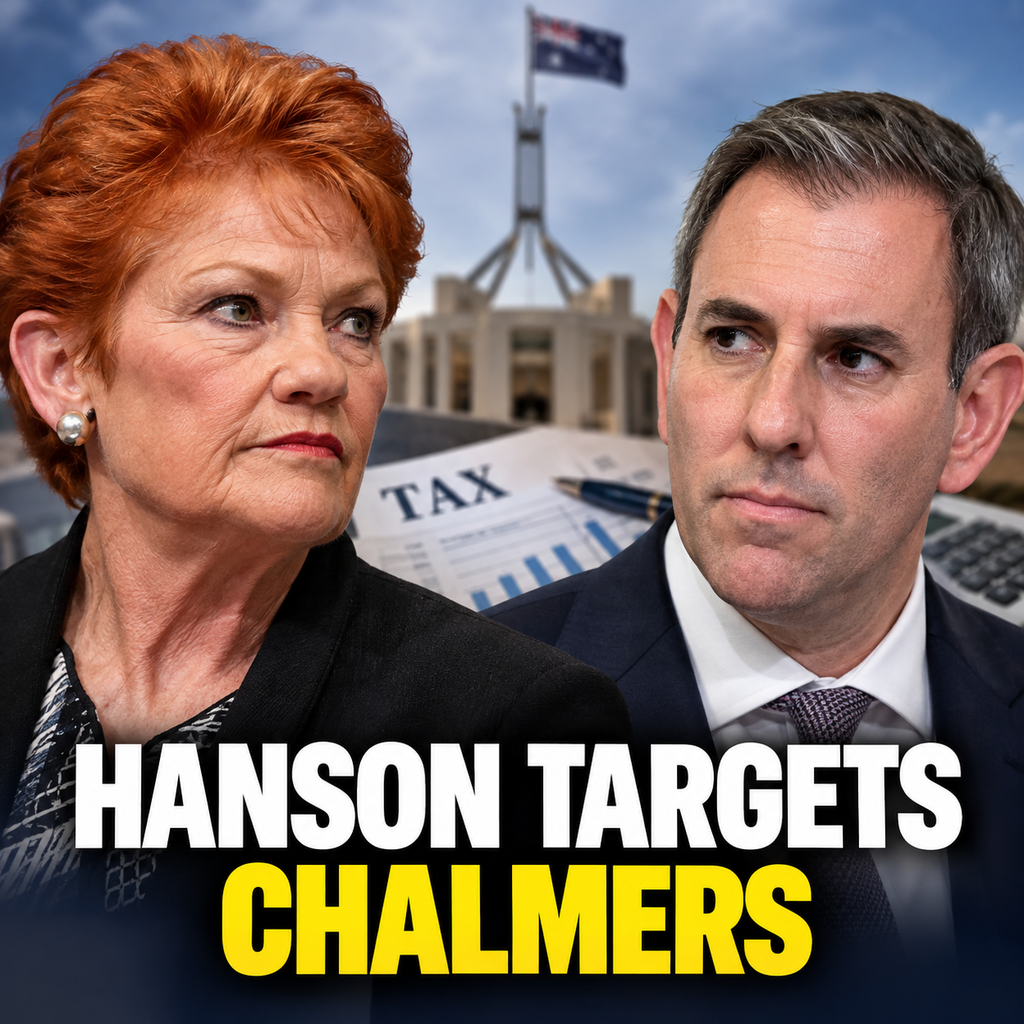
Pauline Hanson has used a business leaders’ gathering to launch a pointed attack on Treasurer Jim Chalmers, arguing that the Albanese government lacks the practical private-sector experience required to understand how Australian businesses operate. The One Nation leader’s message was a political one, but it was delivered to an audience concerned with a more immediate question: how companies manage cash flow, rising overheads and the cost of employing people.
Hanson portrayed the government as too heavily focused on regulation and taxation while insufficiently attentive to the businesses that create jobs and generate revenue. Her argument was not a finding about the Treasurer’s competence. It was an opposition politician’s criticism, accompanied by a pitch for One Nation’s approach to taxes, energy, migration and business regulation.
The distinction matters because the debate is not simply about which political figure has worked in a private business. Business owners must make decisions under the tax and payments rules in force, regardless of who wins the argument over experience. The costs of accepting payments, financing an overdue invoice or investing in equipment can have consequences that are more concrete than a parliamentary insult.
One of the sharpest practical points in the controversy concerns card payments. Australian businesses have had to adjust to changes in the way payment surcharges are treated. Under the nationally applicable rules published by the government, businesses cannot add card-payment surcharges for transactions using major card networks, including eftpos, Visa, Mastercard and American Express. The restriction does not mean payment processing has become free. Merchants still need to examine the fees charged by payment providers and decide how those costs fit into ordinary pricing.
That distinction is essential for customers as well as businesses. A retailer unable to add a separate card surcharge may need to absorb processing expenses or account for them in the advertised price of goods and services. The result will depend on the merchant’s costs, competitors and pricing decisions. It would be misleading to claim that every consumer faces an automatic increase or that the rules eliminate transaction costs altogether.
Tax payment methods have been another flashpoint. A planned change to the Australian Taxation Office’s acceptance of credit-card payments raised concerns among business groups about cash-flow management. The government subsequently announced a transition intended to allow affected businesses more time to adapt. Chalmers rejected the suggestion that Prime Minister Anthony Albanese had overruled him, characterising the decision as a coordinated government response. The separate dispute illustrates why business payment costs have become politically sensitive. Chalmers’ comments concerned the government’s handling of the ATO payment issue, not Hanson’s remarks at the summit.
For some enterprises, access to short-term credit can bridge the gap between paying wages and collecting money owed by customers. Using a credit card to pay a tax liability, however, is not the same as receiving a tax concession. Any interest, processing fees and repayment terms can outweigh the convenience of paying later. A business facing financial pressure must distinguish a change in payment method from a reduction in the actual amount of tax due.
Small-business taxation is also more complicated than a promise to cut red tape suggests. Eligible operators can claim ordinary deductions for expenditure incurred in earning assessable income. Certain equipment may qualify for immediate deductions under simplified depreciation rules, but eligibility and thresholds depend on the income year, business turnover, cost of the asset and when it is first used. The existence of a deduction does not turn the purchase into free equipment. It reduces assessable income under the applicable rules, not necessarily the price paid to a supplier.
That is why a useful discussion of business tax needs to separate the company tax rate, the GST, deductions, instalment timing and the administrative effort of keeping records. Each affects a different part of a firm’s finances. A policy that accelerates a deduction might help cash flow without changing the total profit a business earns. Another that changes the price or availability of a payment service can create an operational adjustment without changing income tax rates.
Hanson also tried to position One Nation as a business-friendly party while explaining that her migration approach would not exclude every skilled worker. That matters to employers who depend on hard-to-find labour. Yet a political assurance is not an enacted migration rule, and the effect on hiring would depend on how any future policy defined occupations, visa access and employer obligations. Businesses planning recruitment cannot assume the details of an opposition proposal are already law.
Chalmers, for his part, has defended the government’s economic management in other settings. His comments form part of the wider contest over living costs and productivity. No point-by-point response from the Treasurer to Hanson’s summit criticism has been established.
The question facing business owners is whether any party can show, in precise terms, how its proposals would alter real operating costs. A lower tax rate, cheaper energy, fewer compliance hours and better access to staff may sound attractive, but each has different budget implications and trade-offs. The strongest test of the political promises will be what they mean for invoices, payroll, payments and investment rather than the force of the personal criticism.
There is a further distinction between cash flow and profitability that often disappears from business policy announcements. A profitable business can still struggle to meet a tax instalment or payroll obligation when clients pay late. Conversely, a company may have cash available after borrowing without having made a profit. Credit availability, payment terms and tax timing affect liquidity, while pricing power, productivity and input costs help determine sustainable earnings. A reform aimed at one problem should not be sold as a guaranteed answer to the other.
Merchant acquiring illustrates the trade-off. Providers may charge a percentage of transaction value, a fixed fee, equipment rental, service charges or some combination. A small business with many low-value transactions may experience that structure differently from a business taking fewer large payments. Comparing providers therefore involves reading the total schedule of charges and settlement timing, not just the advertised percentage. The prohibition on customer-facing card surcharges changes how costs are recovered; it does not remove the need to compare competing payment arrangements.
There are also consequences for bookkeeping. A trader taking electronic payments must reconcile settlement amounts, refunds, transaction fees and recorded sales. Accurate records matter for GST and income-tax reporting. The administrative cost of compliance includes staff time and software as well as any fee paid to an external accountant. When political leaders promise to simplify regulation, business owners need to know which reporting obligation would actually change and whether it would reduce work or merely shift it elsewhere.
Energy is another line of business spending Hanson highlighted. Electricity and gas bills can be major expenses for hospitality operators, manufacturers, farmers and refrigerated transport businesses. But the influence of government policy is not uniform across those activities. Wholesale costs, network charges, retail contracts, consumption patterns and equipment efficiency all affect bills. A credible claim that one party will deliver cheaper energy must explain the mechanism and the likely timeframe, rather than asserting that lower prices automatically follow from deregulation.
Employment costs similarly go beyond the wage rate. Employers must consider superannuation, leave provisions, workplace insurance, recruitment and training. Some payments are mandatory and others depend on industry agreements or contractual terms. A policy described as cutting business costs may also affect employees. The accounting impact and the distribution of benefits between employers and workers are therefore separate issues that deserve scrutiny.
The question of business finance provides another test. A loan can fund equipment or help a firm bridge a temporary shortfall, but the true cost depends on interest, fees, security requirements and repayment obligations. A credit facility is neither revenue nor a substitute for reliable customers. Rising finance expenses can also reduce the benefit of a tax deduction or a lower processing fee. These trade-offs differ between a business that owns its premises and one paying commercial rent, or between an exporter and a local service provider. That variation helps explain why a single national tax proposal can have different commercial effects.
None of these practical considerations proves Hanson’s characterisation of Chalmers, and none establishes that One Nation’s proposals would achieve the savings being promised. They explain why the audience for the attack is interested in concrete numbers. To assess a proposal seriously, a business owner needs eligibility rules, implementation details and a realistic estimate of total costs after the change. Public debate is improved when campaign rhetoric is tested against that standard.
The ACCI conference was specifically concerned with productivity, tax reform and cutting compliance burdens, giving the speech a clear business-policy setting. That does not mean participating employers endorsed every proposal Hanson raised. A business audience and the political claims made to it are different sources of authority. The figures needed to establish a saving would still have to come from legislation, financial modelling or comparable evidence, not the atmosphere of the room.
Hanson’s attack has intensified the dispute. The deeper issue is whether Australian businesses receive clear, workable rules for the practical decisions they make every day. The practical effect on business operations will outlast the political rhetoric.