Former prime minister Paul Keating, widely regarded as the architect of Australia’s compulsory superannuation system, has proposed what could become the biggest overhaul of the nation’s retirement income framework in decades.
Keating has urged the Albanese government to integrate elements of Centrelink with Australia’s private superannuation sector, arguing that retirees should no longer have to navigate two separate systems to fund their retirement.
The proposal comes as Australia confronts the growing challenge of supporting an ageing population while ensuring retirees have confidence to spend the savings they accumulated during their working lives.
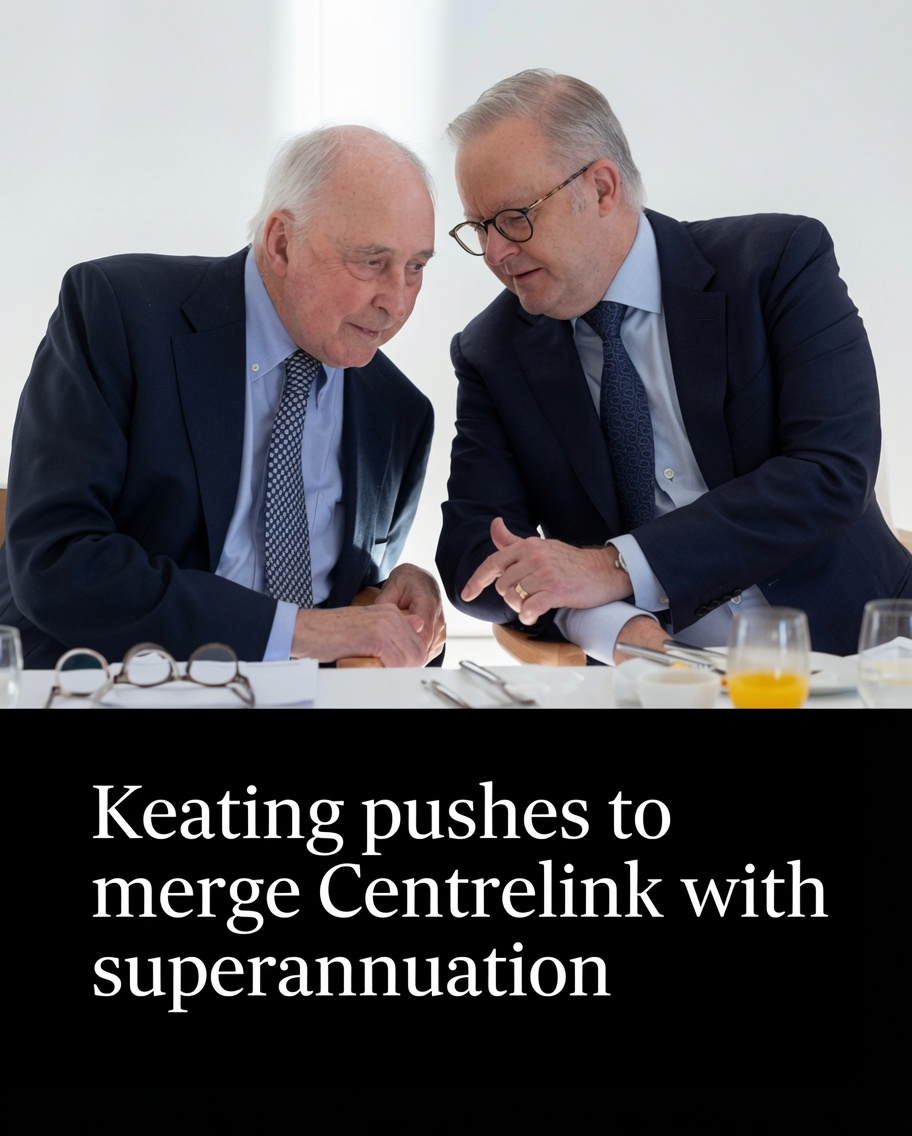
Speaking about the idea, Keating argued that technology now makes it possible to create a far more seamless retirement experience, replacing complicated paperwork with a single integrated system.
Australia’s retirement income model currently rests on three pillars: the Age Pension funded by taxpayers, compulsory employer superannuation contributions, and voluntary private savings.
Although the system is frequently praised internationally for helping Australians build retirement wealth, many retirees still find the interaction between superannuation rules and Centrelink’s pension eligibility requirements difficult to understand.
Applying for the Age Pension often requires extensive documentation, detailed financial disclosures and ongoing reporting obligations. For many older Australians, especially those with multiple income sources, the process can become confusing and intimidating.
Keating believes much of this complexity could disappear if superannuation funds became the primary interface for retirement income administration.
Under his vision, retirees could deal largely with their super fund while the necessary information flowed securely between funds and government agencies, creating what he described as a single retirement system.
The proposal emerged during discussions about improving retirement outcomes after Aware Super chief executive Deanne Stewart highlighted another growing concern facing retirees.
According to Stewart, many Australians are withdrawing only the legal minimum from their superannuation accounts despite having substantial retirement savings.
Rather than enjoying the income their savings were intended to provide, many retirees are deliberately limiting withdrawals because they fear running out of money later in life.
This phenomenon has become increasingly familiar across the superannuation industry.
Financial advisers have long observed that uncertainty about life expectancy, healthcare costs, residential aged care expenses and market volatility often encourages retirees to preserve their balances instead of spending them.
Ironically, some retirees finish their lives with significant remaining super balances that were never used to improve their retirement lifestyle.
Stewart argued that better integration between super funds, the Australian Taxation Office and Services Australia could help members understand their full retirement income picture, including any Age Pension entitlement, making them more confident about appropriate spending decisions. Recent industry discussions have increasingly focused on secure data-sharing rather than complete institutional mergers.
Australia’s compulsory superannuation system has grown into one of the world’s largest retirement savings pools, now worth around $4.5 trillion.
When Keating introduced compulsory employer contributions during the early 1990s, the objective was to reduce long-term dependence on the Age Pension while allowing Australians to accumulate private retirement savings throughout their careers.
More than three decades later, superannuation has become central to Australia’s retirement policy, but the Age Pension continues to play a vital role.
Many retirees receive either a full or partial pension alongside income generated from their superannuation accounts.
The combination of both income sources means retirees frequently interact with separate organisations, separate rules and separate reporting requirements.
Supporters of greater integration argue this duplication creates unnecessary complexity.
The concept has attracted interest from several parts of the retirement industry.
Industry leaders have previously argued that super funds are already well placed to provide retirement guidance because they maintain long-term relationships with members throughout their working lives.
By extending those relationships into retirement administration, they believe Australians could receive more coordinated assistance as they transition from employment into retirement.
Recent commentary from industry figures has emphasised that stronger cooperation and secure information sharing between super funds and Services Australia could make pension applications simpler while helping retirees understand all available sources of retirement income.
However, Keating’s proposal also raises significant policy questions.
One concern centres on privacy.
Greater integration would require more extensive sharing of personal financial information between government agencies and private superannuation funds.
Although supporters argue modern digital systems can safely manage this information, critics caution that any expansion of data sharing must include robust privacy protections and clear accountability.
Others question whether private superannuation funds should become more deeply involved in administering a taxpayer-funded welfare payment.
Some Coalition figures have argued that Australians’ private retirement savings should remain clearly separate from the public Age Pension system, warning against blurring institutional responsibilities.
The debate also highlights broader questions about Australia’s ageing population.
As life expectancy has increased, retirees are spending more years in retirement than previous generations.
Longer retirements create greater uncertainty about how quickly savings should be spent.
Most account-based pensions require minimum annual withdrawals, but many retirees choose not to draw significantly more than those minimums even when doing so may be financially sustainable.
Economists describe this as the “fear of running out” problem.
Without confidence about future income, retirees may unnecessarily restrict spending, reducing their quality of life despite having substantial accumulated assets.
Improving information, simplifying retirement planning and better coordinating pension entitlements are therefore becoming increasingly important public policy objectives.
The discussion also comes as Australia’s retirement system continues evolving through other reforms.
Recent changes have included the introduction of Payday Super, requiring employers to pay super contributions at the same time as wages, alongside adjustments to contribution rules, tax settings and retirement balances. These reforms are intended to strengthen retirement savings while improving transparency for workers throughout their careers.
Whether Keating’s proposal ultimately becomes government policy remains uncertain.
Transforming Australia’s retirement administration would require substantial legislative changes, extensive consultation with the superannuation industry, Services Australia, privacy experts and consumer groups.
It would also involve significant investment in digital infrastructure to ensure secure communication between government and private providers.
Even so, the proposal has reignited discussion about whether Australia’s retirement system has become unnecessarily complicated for the people it is designed to serve.
As more Australians retire with significant superannuation balances, policymakers face growing pressure to ensure those savings work alongside the Age Pension in a way that is simple, efficient and understandable.
For Keating, whose compulsory super reforms fundamentally reshaped Australia’s retirement landscape more than 30 years ago, integrating public and private retirement systems represents the next logical evolution.
Whether Australians embrace that vision will depend on balancing convenience with privacy, efficiency with accountability, and innovation with public trust.